Skip to content
New: our white paper on AI-generated fake bank statements. Get it
Se connecter
  1. Home
  2. Solutions
  3. KYC and KYB

OCR extraction and document verification for KYC & KYB

The document automation tool that combines state of the art OCR with authenticity checks on every document.

  • 22k+ users
  • SOC 2 and GDPR-compliant
  • Try for free
4.6 / 5 on Trustpilot
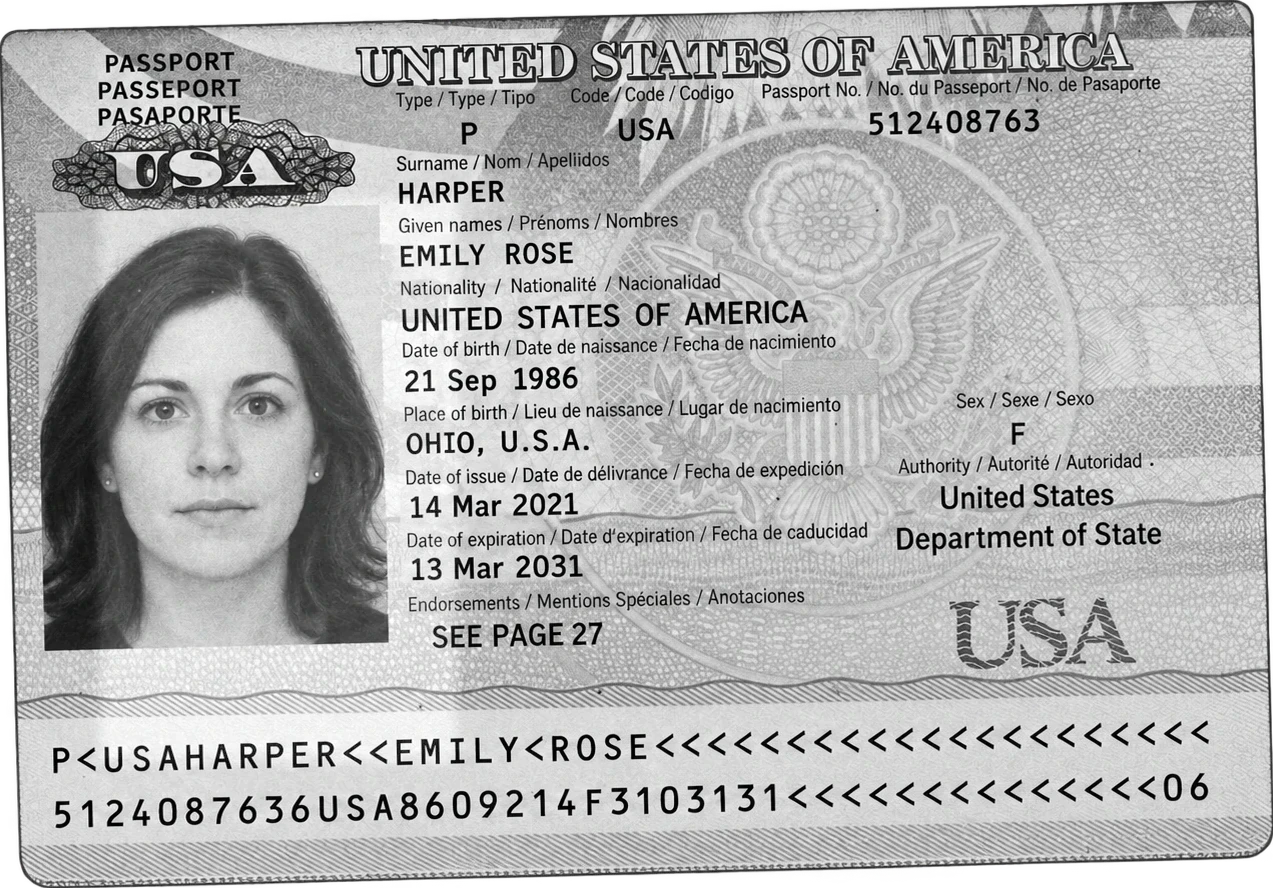
Sample US passport being scanned

The document checker used by insurers, banks and large companies

4.6 / 5 on Trustpilot
In short

Which documents are required for KYC and KYB verification?

For an individual, a KYC file gathers a valid government issued photo ID, a recent proof of address and, depending on risk, proof of income or source of funds. For a company (KYB), add a registration certificate or register extract, the articles of association, the identity of the beneficial owners and bank details in the company's name. The exact list depends on the country and on your risk policy.

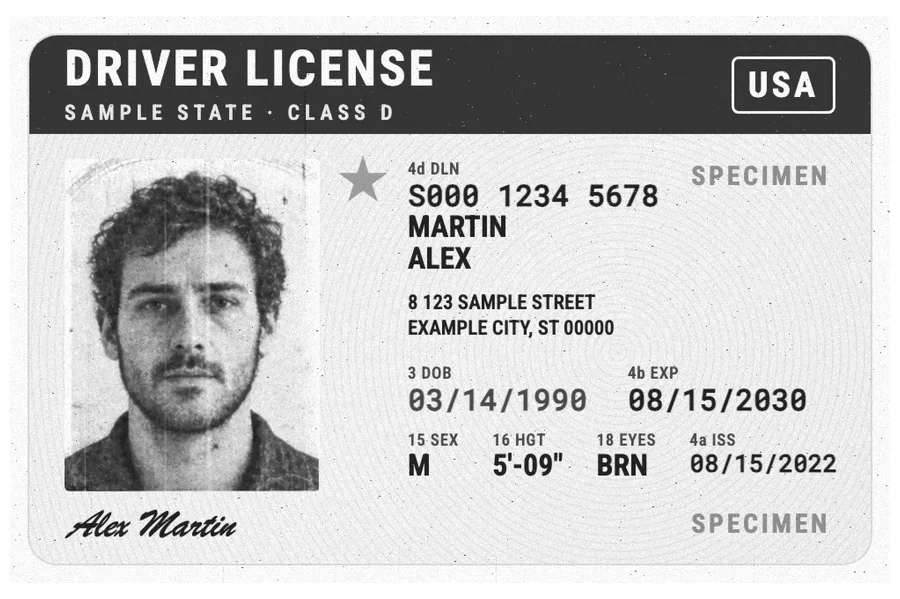
  1. IdentityID card, passport or residence permit, valid. The selfie and liveness belong to biometric tools.
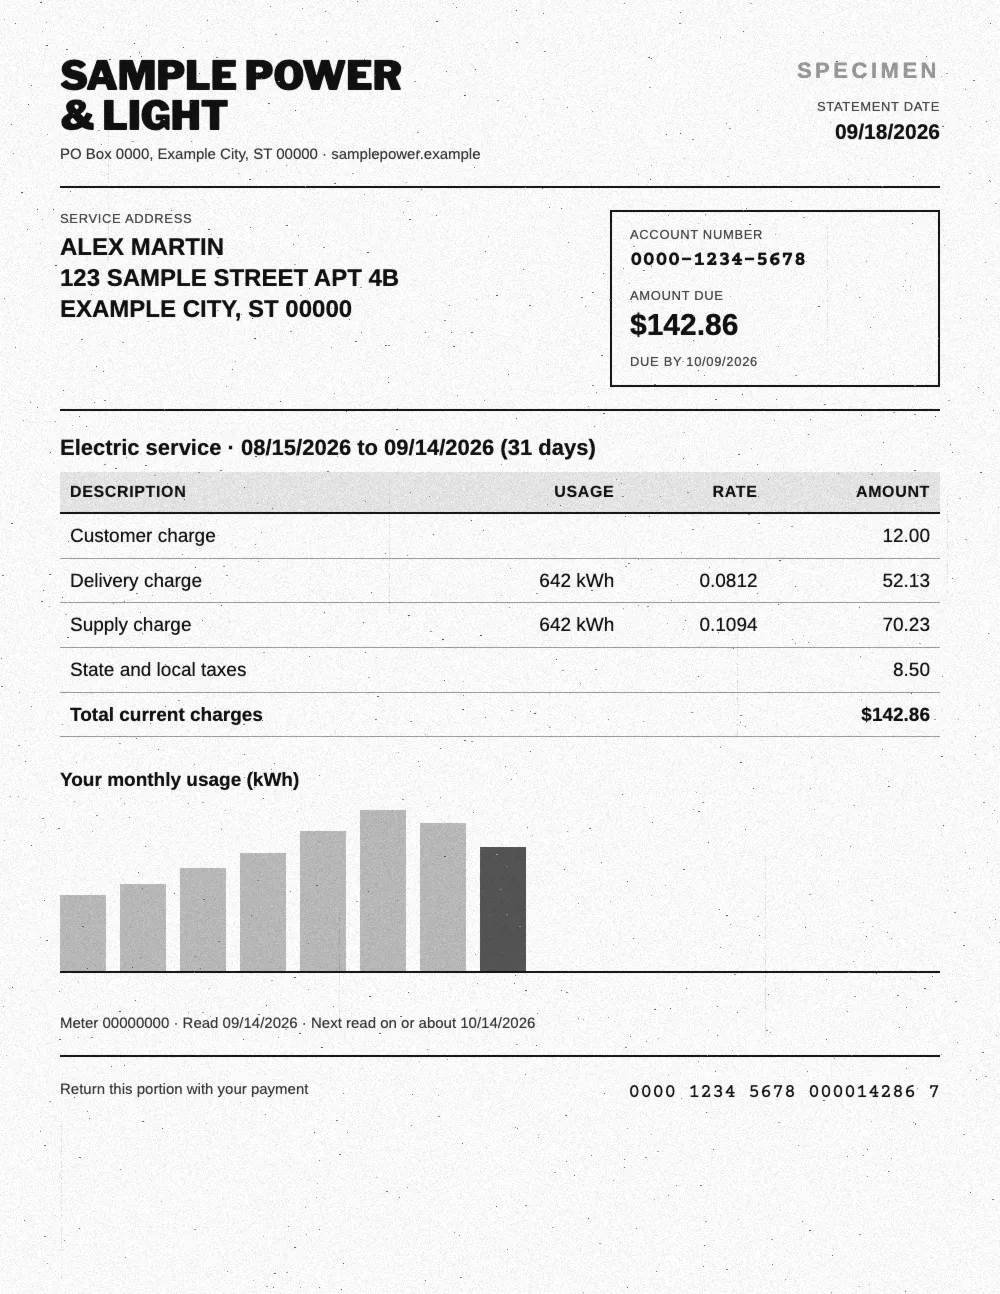
  2. AddressUtility or phone bill, bank statement, tax document: recent, in the customer's name and at the declared address.
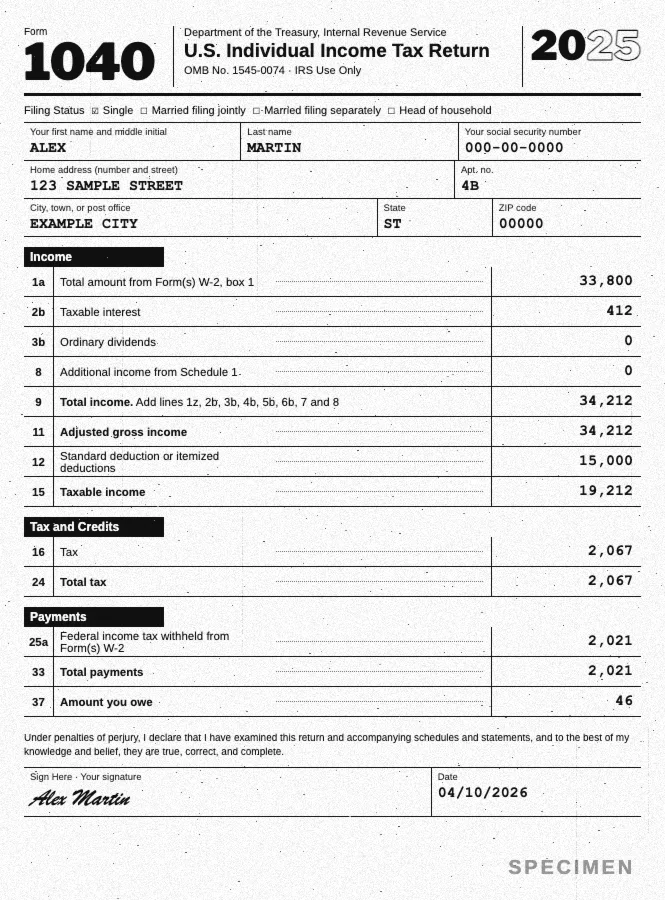
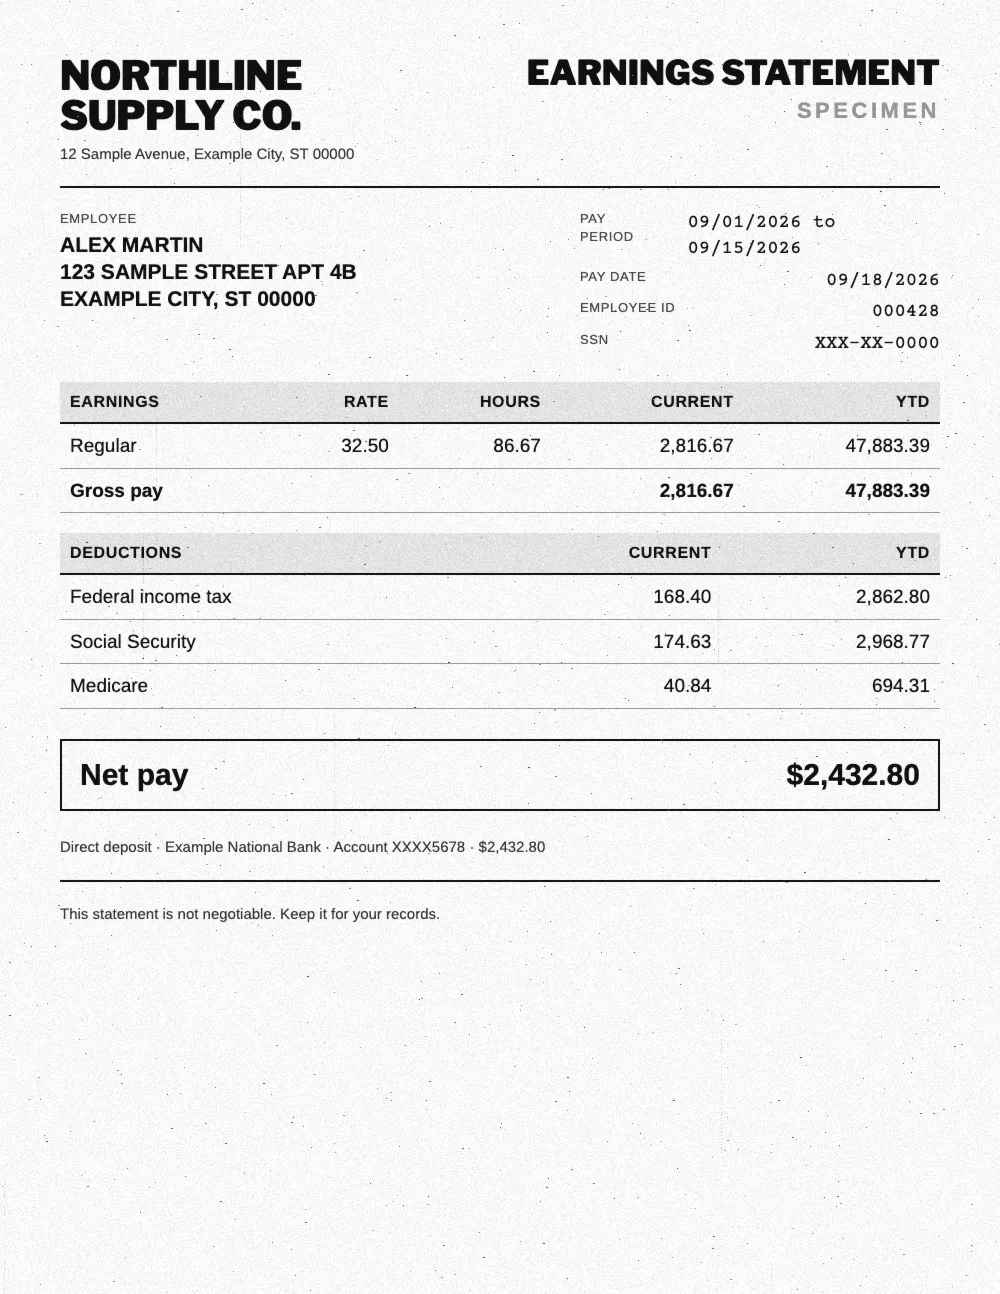
  3. Income and fundsPay stubs, tax documents, statements: asked under enhanced due diligence or to justify the source of funds.
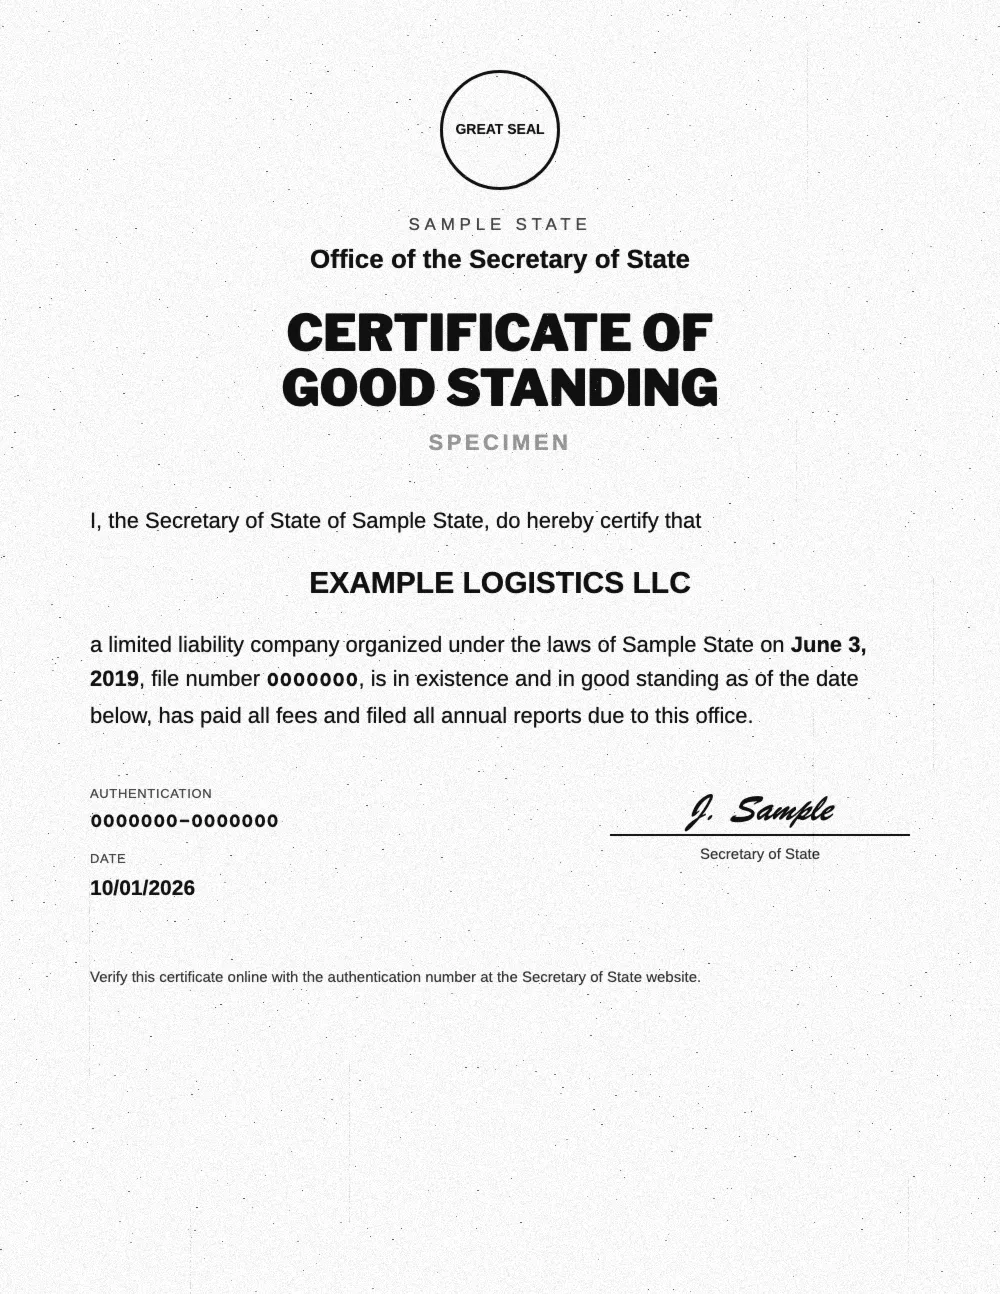
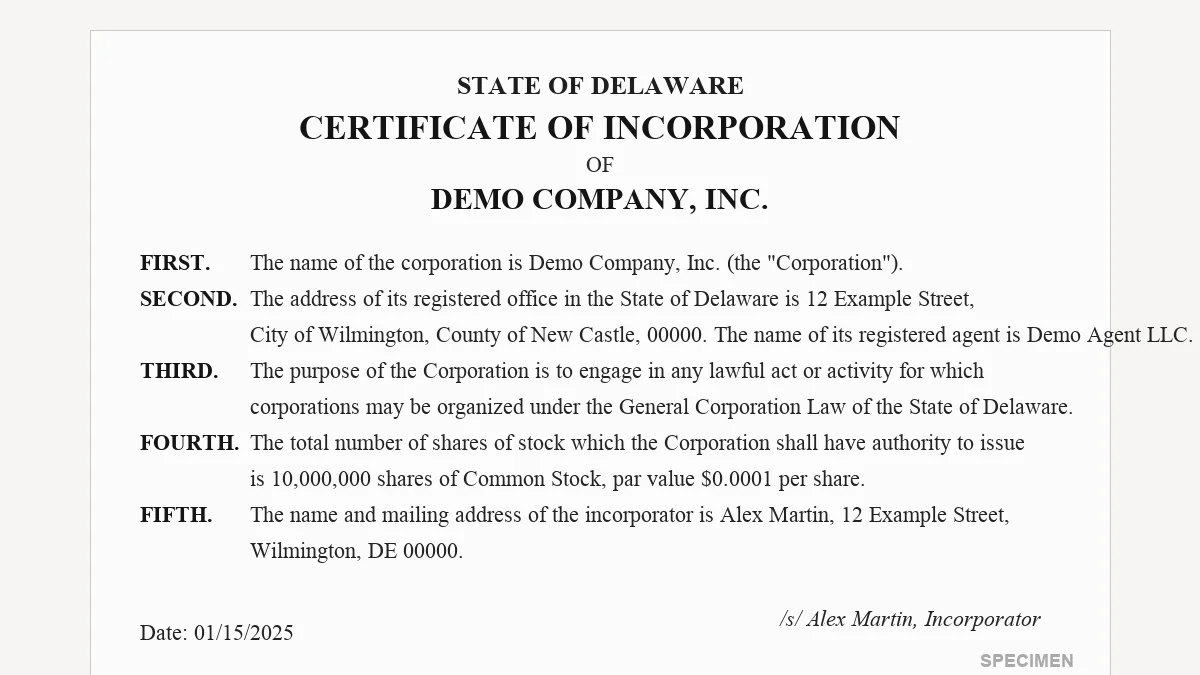
  4. CompanyRegistration certificate or register extract, articles of association up to date, list of directors.
  5. Beneficial ownersMore than 25% of shares or voting rights in the UK and France, 25% or more in the US, or control by other means.
  6. Bank detailsAccount in the customer's or the company's name. In France, a first payment from that account counts as a remote verification measure.
Method

How fake documents get through KYC onboarding

Biometrics made a fake identity harder to pass in front of the camera. Fraudsters moved to the documents around the identity, which nobody looks at closely.

The proof of address, weakest link

The easiest document to fake: a PDF bill with the name, address and date replaced. Most bills carry no verification code, so the file itself has to speak: producer software, fonts, and the date of the last save against the date printed.
The substituted bank details

Fraud takes two forms: an account in a third party's name, or a document edited to match the declared identity. Koncile checks the holder, the account number check digits and the bank, then verifies that the file has not been modified.

UBO verification: the edited register extract and the shell company

A register extract is a PDF, so it can be edited: date, director, capital. Koncile cross checks the company number with the registers, compares the extract with the register's template and reads its metadata.

Koncile does not replace biometric identity verification: the biometric provider verifies the person, Koncile verifies the file.

Checks

KYC OCR: read and check every document

KYC OCR is first about no longer retyping. At Koncile, the same reading serves the check: the extracted fields and the fraud score arrive in the same response.

KYC automation: structured fields, not raw text

A KYC file needs fields, not raw text: names, date of birth, document number, address, account number, directors. Koncile uses one template per document type, with over 99% accuracy on key fields, on PDFs as on photos.

KYC document verification: the customer's name on every document

The simplest check pays the most: each document must be in the name of the person signing up. At Meelo, a credit fintech, Koncile reads the supporting documents at onboarding and flags any document in a third party's name.

Alongside Onfido, Veriff, IDnow or Sumsub

These solutions verify the person: selfie, liveness, face match. Koncile verifies the file: authentic or edited, the ID and every other document around it. 1stKYC integrates Koncile through the API inside its own product.

A readable reason, test by test

A compliance team must explain a refusal, to the customer as to the regulator. Koncile returns a score from 0 to 100 and a reason for every test, calibrated to avoid false alerts.

AI based KYC and AI for AML: what each model does

Identity AI matches a live face with the ID photo: the biometric provider's job. KYC AI, as Koncile practises it, reads every document and judges whether the file was edited or generated. AML AI watches transactions; Koncile does not do that part.

Case studies

What AML rules ask of documents in the EU, the UK and the US

Three regimes, one idea: identify the customer, then verify on documents or information that do not come from the customer alone. Here is what is true and sourced.

EU: from national codes to a single regulation in 2027

Each member state applies its own transposition today. From 10 July 2027, the AMLR (Regulation (EU) 2024/1624) applies the same vigilance rules across the Union, under the new authority AMLA.

UK: the Money Laundering Regulations 2017

Regulation 28 requires firms to identify the customer and verify identity on documents from a reliable, independent source. Since 18 November 2025, directors and persons with significant control must also verify their identity with Companies House.

US: the CIP and CDD rules

The CIP rule (31 CFR 1020.220) collects name, date of birth, address and an identification number, then verifies them through documents. The CDD rule (31 CFR 1010.230) adds beneficial owners holding 25 percent or more.

This summary does not replace your compliance officer or your regulator's guidance.

Data

What onboarding files taught us

What companies say about document fraud, and what we see in our customers' flows.

1 in 5working adults in France already faced a forged document (Ipsos barometer, 2026)
7%of companies consider themselves fully prepared for these risks (same barometer)
5%of files manipulated or transformed across 1.6 million documents processed by Koncile
30+external databases cross checked, from company registers to data leaks

One working adult in five has already seen a forged document, and barely one company in fourteen says it is ready. In our flows, 5% of files show a manipulation or a transformation. Transformed does not mean fake, so Koncile calibrates each check by issuer and by channel.

Source: Ipsos barometer, 2026; Koncile data 2026.

Clients

They verify their files with Koncile

See all our customers

KYC platform that calls Koncile through the API inside its own flow, notably on Belgian ID cards, with one requirement: a fraud reason that can be explained and defended.

One flow for very different documents: ID card, bank details, private hire licence, driving licence, no claims statement, vehicle registration, company extract, lease and photos.

Supporting documents read at onboarding, customer's name verified on every document, income rules applied and account number extracted for the direct debit mandate.

Read the case study

AMOM

Company register extracts checked at onboarding, with an anti money laundering lawyer keeping the final say on flagged files.

Frequently asked questions

Short answers, with figures when we have them.

Talk to us
  1. For an individual: a valid government issued photo ID, a recent proof of address and, depending on the risk level, proof of income or source of funds (pay stubs, tax documents, statements). For a company: a registration certificate or register extract, articles of association, the identity of directors and beneficial owners, and bank details. The US CIP rule names a driver's license or passport for individuals and certified articles of incorporation or a business license for entities.

  2. KYC (Know Your Customer) verifies a natural person: identity, address, source of funds. KYB (Know Your Business) verifies a company: its existence in the register, its directors, its beneficial owners and its bank account. A KYB always contains KYCs, those of the directors and the beneficial owners.

  3. No, it completes it. Onfido, Veriff, IDnow or Sumsub verify the person: selfie, liveness, face comparison. Koncile verifies the files: edits, metadata, issuer's template, content consistency, on the ID document as on the proof of address, bank details, register extract or articles. It integrates through the API into an existing flow.

  4. The set of checks a bank runs before and during a relationship to know who its customer is: identity, address, activity, source of funds, and for a company its directors and beneficial owners. In the EU it stems from the anti money laundering directives, in the UK from the Money Laundering Regulations 2017, in the US from the CIP and CDD rules. In each case, KYC verification means verifying on documents or data that do not come from the customer alone.

  5. The KYB process verifies a company rather than a person. KYB requirements, in the UK and the EU as in the US, come down to four checks: the company exists in the official register (name, number, registered office), its directors are who the articles say, its beneficial owners are identified and verified, more than 25% in the UK and France, 25% or more in the US, and its bank account is in its name. KYB verification with Koncile covers the documents behind each step: register extract, articles, beneficial owner declaration and bank details, read and scored for fraud.

  6. In the EU, the AMLR applies directly from 10 July 2027 and harmonises due diligence across the Union; AMLA, the new European authority, is based in Frankfurt. In the UK, identity verification with Companies House is mandatory for directors and persons with significant control since 18 November 2025. In the US, FinCEN issued exceptive relief in February 2026 on re identifying the beneficial owners of existing legal entity customers. In France, the consumer credit reform applies from 20 November 2026.

  7. No general law sets that period for a proof of address: it is market practice, written into each institution's policy. The three month rule in the French Monetary and Financial Code concerns the register extract of a company (article R561-5-1). In practice, a bill older than three months is often refused, and a date made more recent is one of the most common edits.

  8. In France, enter the extract's verification code on Infogreffe's free control service, then check the date, the company number and the directors in the public registers; in the UK, compare with the Companies House record. For a few extracts a month, that is enough. For hundreds, Koncile cross checks the company number with the registers and reads the file: register template, producer software, modification traces.

  9. In the same pass as the reading. KYC OCR turns every document in the file into usable fields (name, date of birth, document number, address, account number, company number) without retyping. Koncile then examines the file (producer software, modification traces), the image (edited areas) and the content (arithmetic, dates, the customer's name), and compares the document with the known documents of its issuer. The same API response contains the extracted fields and the fraud score from 0 to 100, with the reason for each test.

Try Koncile's fraud detection on your own documents

Upload your bank statements, pay stubs or IDs: Koncile extracts the data and flags fakes in seconds.

Talk to an expert